
DEFINITIONS & METHODOLOGY
In this report, "Chilliwack" refers to Greater Chilliwack — East Chilliwack, Sardis, and Chilliwack proper combined into a single market using sales-weighted averages. This gives a fuller picture of the Chilliwack market than any single sub-area on its own.
All prices are 3-month rolling averages, weighted by sales volume, to smooth out the natural month-to-month noise in a market of this size. Months of Inventory (MOI), the key measure of whether conditions favour buyers or sellers, is calculated the same way: average active listings divided by average monthly sales over the three most recent complete months.
Market temperature is read as: 0 to 5 months of inventory, a Seller's Market. 5 to 8 months, a Balanced Market. Over 8 months, a Buyer's Market.
EXECUTIVE SUMMARY
October told two very different stories. In Abbotsford, buyers came back. 171 homes sold, up from 111 in September and 4% more than last October, and it was the busiest month of 2026 for both total and detached sales. Active listings are 17% lower than a year ago, and detached months of inventory has fallen from 10.7 last fall to 8.0, sitting right on the line between balanced and buyer's territory.
Greater Chilliwack went the other way. Only 101 homes sold, less than half the 10-year October average and the second-weakest October since 2005 (only 2008 was lower). Detached homes and condos both read as buyer's markets, with condos carrying the most supply of any segment at 9.8 months.
Prices are still easing in both cities. The average detached home sold for about $1,033,000 in Abbotsford (down 3.0% from a year ago) and $837,000 in Greater Chilliwack (down 4.0%). Condos took the biggest step back, down about 10% to 11% in both markets.
The rate picture shifted on October 28, when the Bank of Canada raised its policy rate to 2.50%, its first increase since July 2023. Fixed rates had already been climbing since September. The bottom line: buyers hold most of the negotiating leverage right now, but borrowing costs are moving against them, which makes a pre-approval and a rate hold more valuable than they have been in years.
MARKET GAUGE
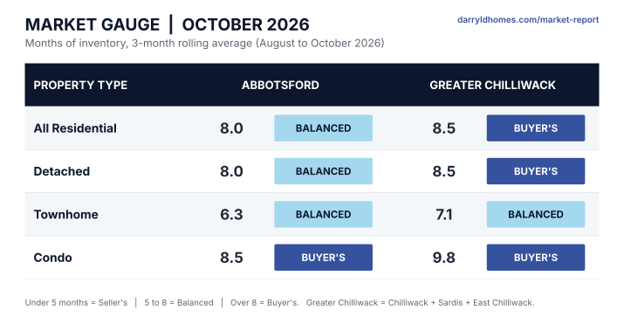
Months of inventory (MOI) tells you how long it would take to sell every active listing at the current pace of sales. Under 5 months favours sellers, 5 to 8 is balanced, and over 8 favours buyers.
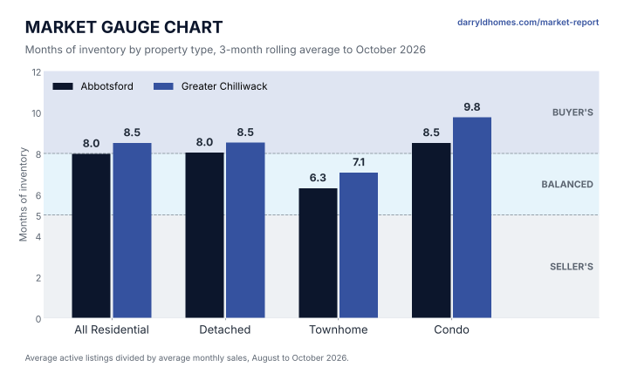
Abbotsford reads Balanced overall at 8.0 months, but it is balanced by the narrowest of margins. Detached sits at 8.0 as well, and only about 12.4% of active detached listings are selling each month, barely above the 12% line that marks a buyer's market. On the ground, with sales still well below normal for this time of year, it feels more like a buyer's market than the label suggests. The encouraging part for sellers is direction: a year ago Abbotsford detached was at 10.7 months. Townhomes are the tightest segment in either city at 6.3 months. Condos remain a buyer's market at 8.5.
Greater Chilliwack has moved the opposite way. Overall MOI is 8.5, up from 7.9 a year ago, and condos have climbed from 7.0 to 9.8 months. Condo inventory is the only segment in either city with more listings than last October. Townhomes are the one balanced spot at 7.1 months.
HOW OCTOBER COMPARES TO HISTORY
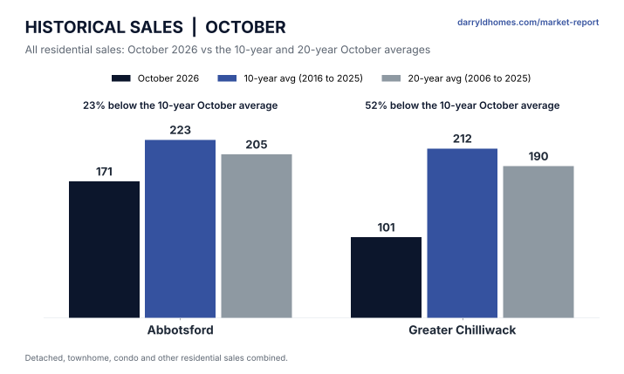
Abbotsford's 171 sales were 23% below the 10-year October average of 223. That is still soft, but it is the best showing this year. Greater Chilliwack's 101 sales were 52% below its 10-year October average of 212, and 29% fewer than last October. Chilliwack proper had just 42 sales and Sardis 56. One month does not make a trend, but it is a number worth watching closely in November.
WHAT PRICES ARE DOING
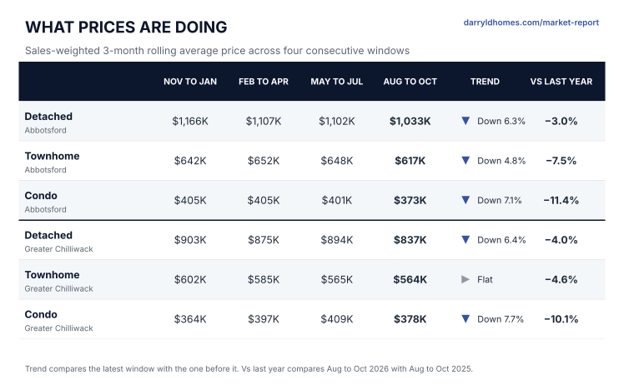
Every segment except Greater Chilliwack townhomes slipped in the latest 3-month window, and all six are below where they were a year ago.
Abbotsford detached averaged about $1,033,000, down 3.0% from a year ago. That is roughly 10% to 17% below the level it held through 2024 and the first half of 2025. Townhomes averaged $617,000 (down 7.5%) and condos $373,000 (down 11.4%). Condos are now about 16% to 21% below their 2024 to mid-2025 level, the largest pullback of any segment.
Greater Chilliwack detached averaged about $837,000, down 4.0% from a year ago and roughly 5% to 12% below its 2024 to mid-2025 level. Townhomes were essentially flat over the last two windows at $564,000 (down 4.6% on the year). Condos averaged $378,000, down 10.1%.
For context, the Fraser Valley Real Estate Board reported its board-wide detached benchmark price down 8.5% from a year ago in October, and called it a buyer's market with sales at 11% of active listings. Local averages above move differently from the board benchmark, but both point the same direction.
UNDERSTANDING INTEREST RATES: FIXED VS VARIABLE
Many buyers assume the Bank of Canada sets all mortgage rates. It does not, and this fall is a good example of why the difference matters.
Variable rates follow the Bank of Canada. The Bank sets the overnight rate, and the big banks set their prime rate from it. Variable mortgages are priced as prime plus or minus a set amount. When the Bank raised its rate by 0.25% to 2.50% on October 28, prime moved from 4.45% to 4.70% the next day, and every variable mortgage moved with it.
Fixed rates follow the bond market. Lenders price 5-year fixed mortgages mainly off the 5-year Government of Canada bond yield, which moves with investor expectations about inflation and future rates. That yield climbed from roughly 2.6% early this year to a high near 3.7% in September as oil prices pushed inflation fears higher. All six big banks raised fixed rates by up to 0.5% over five weeks starting in September, before the Bank of Canada moved at all. BMO's standard 5-year fixed reached 5.14% and TD's advertised 5-year reached 5.39% in October. Those are advertised bank rates; discounted rates through a mortgage broker for well-qualified borrowers are typically lower, so check what applies to you.
The 5-year yield has eased back to about 3.48% in early November. If it holds there, fixed rates may settle, but that is not guaranteed. To put the numbers in real terms, on a $500,000 mortgage with a 25-year amortization, every 0.25% rate change moves the monthly payment by about $68.
The rate hold. If you are thinking about buying in the next few months, ask a mortgage broker about a rate hold. It locks in today's rate for a set period, often 90 to 120 days depending on the lender. It is not binding: you are not committed to that lender, that mortgage or that broker. If rates drop, you can simply take a new hold at the lower rate, and if you decide not to buy, there is no penalty. With rates rising, it is one of the few no-lose moves available to buyers right now.
WHO THE MARKET IS BEST FOR
DOWNSIZERS AND EMPTY NESTERS
If you own a detached home and want to move into a townhome or condo, the math has improved, especially in Abbotsford. Detached prices there fell about $32,000 over the past year, but townhomes fell about $50,000 and condos about $48,000. The gap between an average detached home and an average townhome widened from about $398,000 to $416,000, so a typical trade-down now frees up roughly $18,000 more than it did a year ago. The detached-to-condo gap grew too, to about $660,000.
The challenge is the selling side. Your detached home is competing in a market where buyers are taking their time, so pricing it right from day one matters more than ever. In Greater Chilliwack the trade-down gap actually narrowed slightly, from about $280,000 to $273,000 between detached and townhome, and the sales slowdown there means you should plan for a longer selling timeline. Buying your next place first without a firm sale is a bigger risk in Chilliwack than in Abbotsford right now.
UPSIZERS
Moving up is a mixed picture. In Greater Chilliwack, the step from an average townhome to an average detached home shrank by about $7,000 to roughly $273,000, and detached buyers have plenty of choice at 8.5 months of inventory. That is a genuinely good setup for a move-up buyer, as long as your current home is priced to sell.
In Abbotsford, the step up widened to about $416,000, and your townhome sits in the tightest segment in either city, which helps you sell it but means the detached home you want is the side holding its value better. Higher borrowing costs hit upsizers hardest because the new mortgage is usually larger, so get your rate held before you list.
FIRST-TIME BUYERS
On price and selection, conditions are the best they have been in several years. Condos are a buyer's market in both cities, with average prices down about 10% to 11% from a year ago and room to negotiate. Abbotsford condos average about $373,000 and Greater Chilliwack condos about $378,000.
The honest trade-off is rates. Variable payments went up on October 29, and economists expect at least one more increase in early 2027. Fixed rates are higher than they were in the summer. A buyer who waits for lower prices could end up paying more each month anyway. Get pre-approved, hold a rate, and shop with the confidence that sellers in this segment are listening to offers.
A FEW THINGS WORTH WATCHING
Greater Chilliwack's October sales were unusually weak, and a single month can overstate a trend. If November sales stay near this level, expect more price pressure there, particularly on condos. In Abbotsford, the falling inventory is a quiet positive for sellers, but the market is balanced by the thinnest of margins and could tip either way. Rate risk runs in one direction for now: the Bank of Canada has said it may need to raise rates further, and its next decision is scheduled for December 9. Finally, energy prices tied to the ongoing Middle East conflict and new US tariffs are the two biggest outside factors that could move rates and confidence over the winter.
SPOTLIGHT - GREATER CHILLIWACK CONDOS
This is the most buyer-friendly segment in either city right now. Months of inventory has jumped from 7.0 a year ago to 9.8, the highest reading in our report. Only about 10% of active condo listings are selling each month, well below the 12% buyer's market line. It is also the only segment in either city where active listings are higher than last October (up 4%), while sales averaged just 20 a month over the past three months.
The average condo price is about $378,000, down 10.1% from a year ago. For a first-time buyer or a downsizer who wants low maintenance, that combination of choice and soft pricing creates real negotiating room: conditions, longer completion dates and price reductions are all on the table. For condo owners thinking of selling, the honest advice is to price at or slightly below recent comparable sales from day one, because the buyers in this segment have plenty of alternatives.
STABILITY TREND
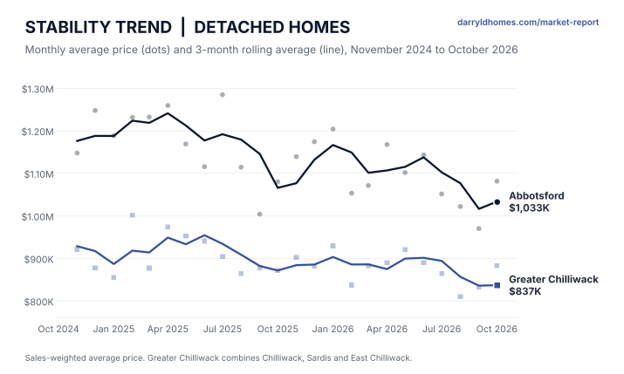
Over the past two years, detached prices in both cities have drifted lower rather than dropped sharply. Single months bounce around (the dots), but the 3-month rolling line shows the real direction. Abbotsford moved between about $1.07 million and $1.24 million through 2025 before easing to about $1,033,000 this fall. Greater Chilliwack held a tighter band of about $870,000 to $955,000 and has slipped to about $837,000. The late-summer step down was the steepest move of the year in both cities. October shows both levelling off for now, with Abbotsford ticking up slightly and Chilliwack flat, though Chilliwack's reading rests on very few sales.
WEALTH TREND
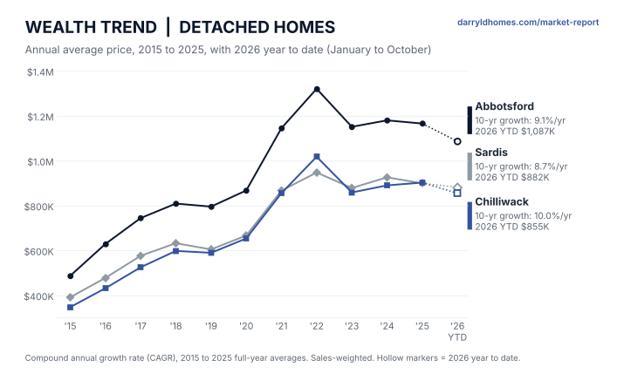
Short-term softness looks different against the long view. From 2015 to 2025, average detached prices grew at a compound rate of about 9.1% a year in Abbotsford, 10.0% a year in Chilliwack and 8.7% a year in Sardis. An Abbotsford detached home averaging about $488,000 in 2015 averages about $1,087,000 so far in 2026, more than double.
All three areas peaked in 2022 and have given back some of those gains. So far in 2026, annual averages are down about 6.8% in Abbotsford, 5.3% in Chilliwack and 2.0% in Sardis compared with 2025. For long-term owners that is a correction within a decade of strong growth. For anyone who bought near the 2022 peak, it is a reminder that real estate builds wealth over long holds, not short ones.
INVESTOR INSIGHTS: RATE SENSITIVITY & MARKET DYNAMICS
RENTAL MARKET
Rents are softening. Rentals.ca reported Abbotsford's average asking rent at $1,819 in September, about 6% lower than a year earlier, after an even steeper annual drop in August. BC asking rents have now declined year over year for more than two years. The most recent CMHC vacancy survey (October 2025) put purpose-built apartment vacancy at 2.8% in Abbotsford-Mission and 3.1% in Chilliwack, both healthier than the very tight levels of recent years. CMHC's 2026 survey is due in December and will show whether vacancies rose further.
SUPPLY AND DEMAND OUTLOOK
New supply is arriving and drying up at the same time. More than 950 new purpose-built rental homes were scheduled to complete in the Fraser Valley in September alone, adding near-term competition for landlords. At the same time, the future pipeline has stalled. MLA Canada counted just two presale launches totalling 76 homes in August across the region, and Abbotsford-Mission housing starts are down 49% year to date. Population growth has also slowed sharply. BC's population fell 0.9% in the 12 months to April 2026, driven by an 18% drop in non-permanent residents, before edging up 0.1% in the spring quarter. Ottawa's updated immigration targets are expected with the federal budget on November 5, and the Prime Minister has signalled that a "controlled increase" may come after recent reductions.
RATE SENSITIVITY AND MARKET DYNAMICS
Every 0.25% increase adds about $68 a month to a $500,000 mortgage, and many investors carry larger, variable-rate loans. As an illustrative example only (not a specific listing), a detached home with a legal suite in the $1 million range financed with 20% down at around 4.5% carries a mortgage payment of roughly $4,400 a month before taxes, insurance and maintenance. With suite rents softening, most of that payment still has to be covered by the owner or a main-floor tenant.
The honest read: cash flow is harder today than it was a year ago, but purchase prices are lower and sellers are negotiating. The investors best positioned now are long-term holders with strong down payments who can ride out near-term rent softness while the shrinking construction pipeline works in their favour over the next few years.
MACRO OUTLOOK
Bank of Canada. The Bank raised its policy rate by 0.25% to 2.50% on October 28, saying inflation has proven higher and more persistent than it expected in July, largely because of energy prices. Governor Tiff Macklem said "There could be a need to raise the policy rate further," and that decisions will be taken one meeting at a time. TD Economics expects one more increase in early 2027 to 2.75%; BMO and Desjardins also expect one more in January. Forecasts beyond that vary widely.
Inflation. Consumer prices rose 3.1% over the year to September, up from 3.0% in August, with gasoline the main driver. Excluding gasoline, inflation was 2.2%. The Bank expects inflation to reach about 3.5% by year end and return to its 2% target around mid-2028.
Economy. Canada's economy grew faster than expected through the middle of the year, but the Bank expects growth to slow in the fourth quarter as new US tariffs take effect. Unemployment has held near 6.5% for several months.
What it means locally. Higher rates and slower population growth are weighing on demand, while falling construction and shrinking listing counts are slowly tightening supply. That tug of war is why prices are drifting rather than dropping. Expect a quiet winter, with the spring market heavily shaped by where rates and bond yields land in early 2027.
Questions about what this means for your home or your next move? Reach out any time for a no-pressure conversation.
Data: Fraser Valley MLS® statistics for Abbotsford, Chilliwack, Sardis and East Chilliwack, January 2005 to October 2026. Rates and economic data: Bank of Canada, Statistics Canada, BC Stats, CMHC, Rentals.ca, MLA Canada, TD Economics and published bank rate announcements, current as of November 4, 2026. This report is for general information and is not financial or mortgage advice.
Buying or Selling? Free home valuation and/or consultation
I look forward to working with you and helping you reach your home ownership goals. Reach out to get in touch and start the process today. I offer:
